Cyber fraud networks exploit gaps in international investigations

New Delhi: A person losing money to an online investment scam in India may report the fraud within minutes, but tracing the stolen amount can become a considerably longer exercise when the transaction involves multiple bank accounts, digital platforms and overseas operators. This difference between the speed of cybercrime and the processes required to investigate it has emerged as a major challenge for law-enforcement agencies.
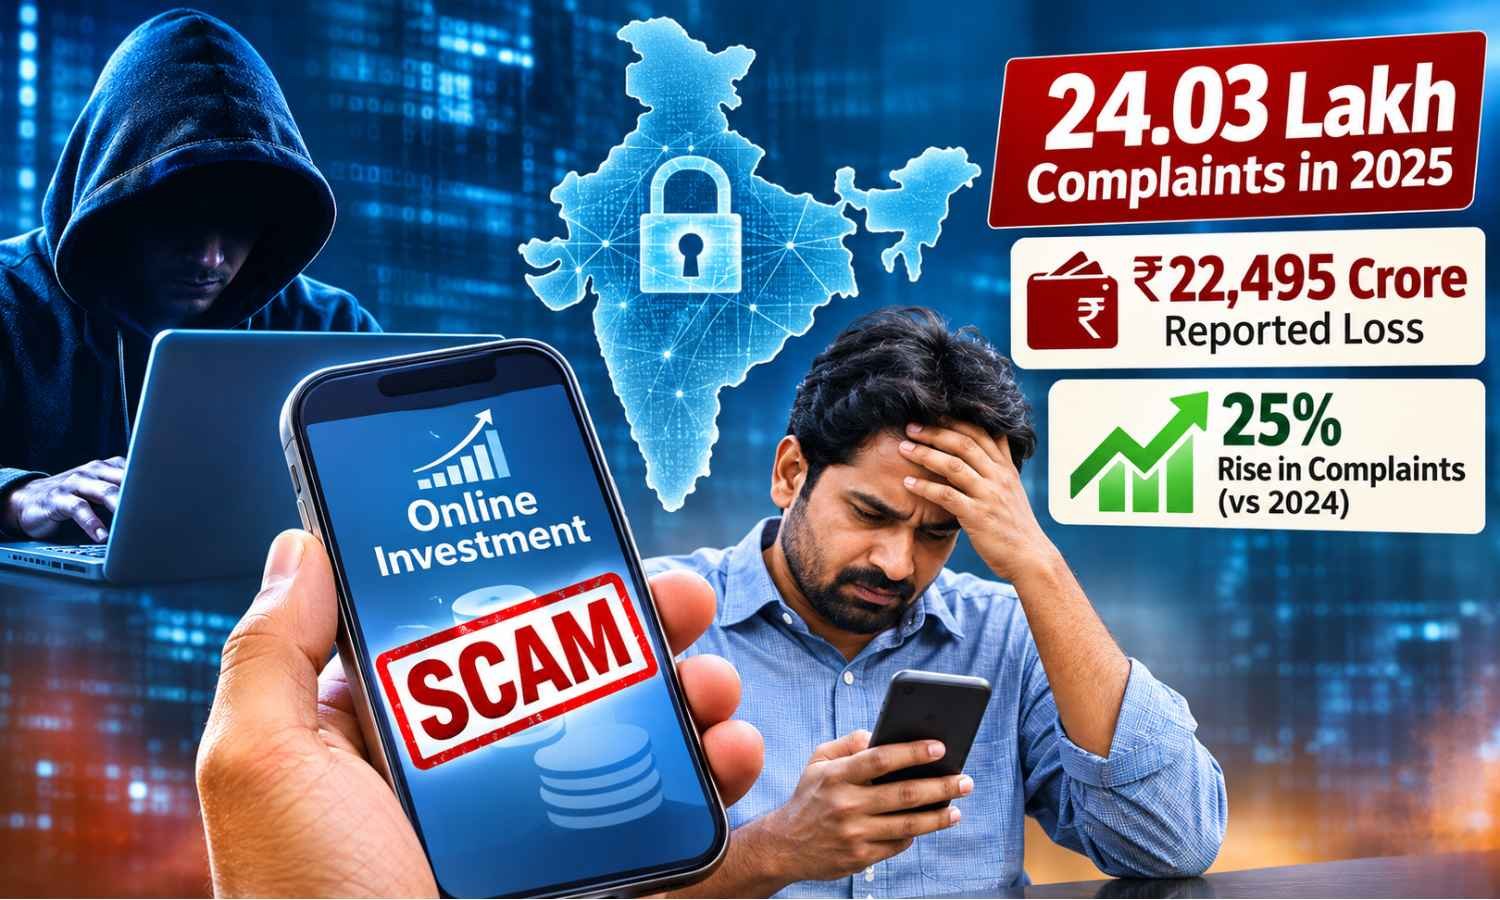
India recorded more than 24 lakh financial cyber-fraud complaints during 2025, involving a reported amount of Rs 22,495 crore. The figures reflect the scale of criminal activity affecting digital payment users, investors and other individuals who increasingly depend on online financial services.
The number of reported complaints rose from approximately 19.19 lakh in 2024 to 24.03 lakh in 2025, representing an increase of about 25 per cent. The reported amount, however, declined marginally, indicating that growth in complaint volumes does not necessarily translate into an equivalent increase in the value of reported fraud.
The figures also require careful interpretation. Amounts reported through the National Cyber Crime Reporting Portal are not necessarily identical to losses finally established after investigation. Money may be frozen or recovered in some cases, while other complaints may require further examination.
How digital fraud becomes difficult to trace
Organised cybercrime can involve several distinct functions, including identifying potential victims, establishing contact, persuading them to transfer money and moving the proceeds through different financial channels.
Investment fraud, impersonation, fraudulent payment requests and deceptive digital communications illustrate the range of methods used to target individuals. Some operations also involve people who provide bank accounts or other facilities for transferring money without being the principal organisers of the crime.
The investigation becomes more complicated when the people directing an operation, the accounts receiving money and the services used to communicate with victims are located in different jurisdictions.
A transaction may appear straightforward to the victim, who sees only the account or payment instructions provided by the fraudster. Establishing the wider network can require examination of financial records, digital communications, account ownership, transaction histories and the circumstances in which the money was transferred.
The growing use of digital platforms creates additional opportunities for criminals to conceal their activities. Accounts can be created using misleading identities, communications can be distributed widely and financial proceeds may move through several intermediaries before investigators identify the destination.
Artificial intelligence adds another concern by making deceptive messages and impersonation attempts easier to prepare at scale. Its use does not necessarily change the underlying nature of fraud, but it can make suspicious communications more convincing and increase the volume of potential approaches to victims.
Why international cooperation matters
Indian authorities can initiate domestic investigations, examine bank records and seek restrictions on accounts associated with suspected fraud. However, obtaining evidence controlled by overseas organisations or authorities may involve additional legal and procedural requirements.
Different countries have their own rules governing financial disclosure, data protection, criminal investigations and the transfer of evidence. Information requested by one country’s investigators may therefore require formal cooperation from another jurisdiction before it can be lawfully obtained.
These processes are important safeguards, but they can also affect the pace of investigations. Difficulties become particularly significant when digital evidence is time-sensitive or criminal proceeds have already passed through several accounts.
Effective cooperation depends on reliable identification of suspects, preservation of records and procedures that allow authorities to exchange information without compromising legal requirements.
The challenge cannot be reduced to an assumption that every overseas jurisdiction is unwilling to cooperate. Differences in legal systems, evidence requirements and investigative resources may affect individual cases in different ways.
Recovery remains a crucial measure
The government has developed mechanisms intended to facilitate the reporting of financial cyber fraud and the interception of suspicious transactions. The National Cyber Crime Reporting Portal and the Citizen Financial Cyber Fraud Reporting and Management System form part of this response.
These arrangements are particularly important because the possibility of preventing further movement of stolen funds may diminish as transactions proceed. Prompt complaints can assist efforts to identify accounts and restrict the transfer of suspected proceeds.
Nevertheless, the amount prevented from moving, the amount frozen and the amount ultimately returned to victims are different measures. They should not be treated as interchangeable when assessing the success of cybercrime enforcement.
Complaint statistics alone cannot establish the proportion of cases solved or the effectiveness of individual investigations. A fuller assessment requires information on recoveries, prosecutions, convictions and the time taken to provide relief to victims.
India’s challenge is therefore not confined to identifying cybercriminals. It also involves ensuring that reporting systems, banks, investigating agencies and international counterparts can respond in a coordinated manner.
As financial services become increasingly digital, the strength of these arrangements will influence public confidence in online transactions. Reducing the gap between the speed of fraud and the speed of enforcement will remain central to protecting users and limiting losses.
